There’s a moment I see often with business owners. They pull up their profit and loss statement, scan the numbers, and feel like they have a handle on things. Revenue looks reasonable. Expenses look… fine. And then tax time rolls around, and everything collapses into the same categories that appear on Schedule C or their business return.
The problem? A tax return is built for the IRS, not for you.
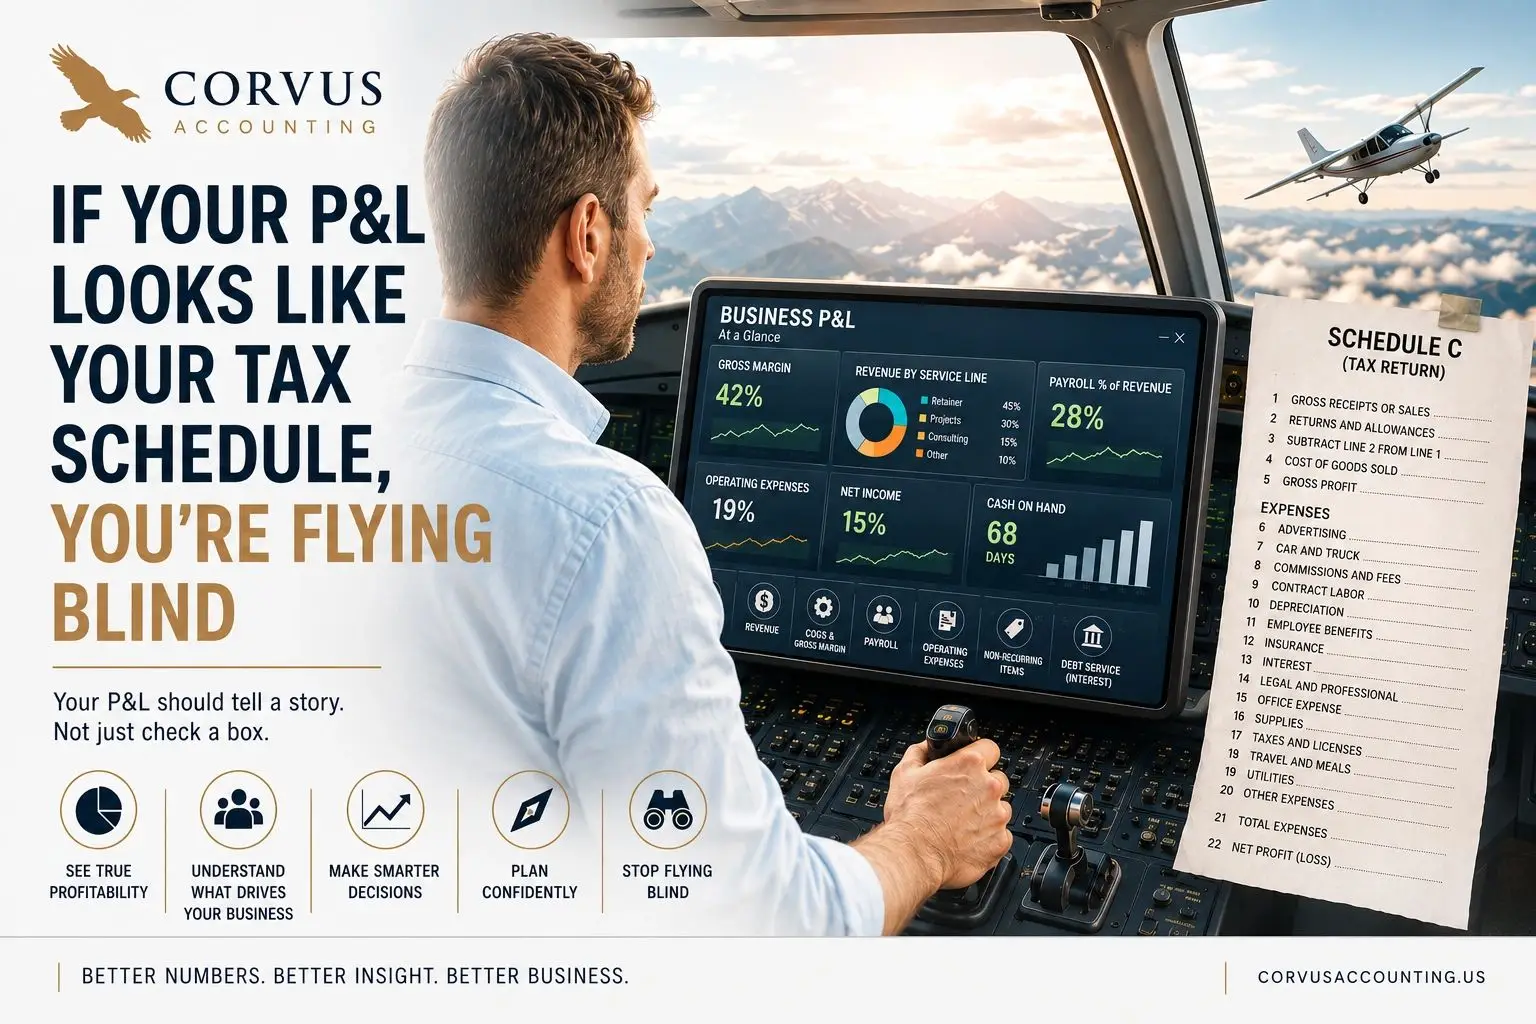
Your P&L — when it’s structured for your business — should tell you a story. It should answer questions like: Where are my margins actually being eaten? Am I making money on my biggest client or just staying busy? What happened in March? When your P&L is organized the same way your tax preparer organizes it, those questions go unanswered. And in small and mid-sized businesses, unanswered questions have a way of quietly costing you money.
Here are the five areas I see business owners overlook most often — and what it’s actually costing them.
1. Revenue Isn’t One Number
Most tax schedules want a single gross revenue figure. But your business almost certainly has more than one revenue stream, and those streams don’t all behave the same way.
A catering company that bundles food, labor, and event coordination into a single “Sales” line has no idea whether the food is profitable, whether the labor is being priced correctly, or whether that “profitable” event contract is actually a breakeven hustle. The same issue shows up in service businesses that mix recurring retainer work with project-based engagements — or product businesses that sell direct-to-consumer alongside wholesale.
When revenue is broken out by type, service line, or customer segment, patterns emerge fast. One revenue stream might carry a 40% margin while another runs at 12%. You can’t see that in a single line.
What to do: Break revenue into at least 2–4 meaningful categories that reflect how your business actually generates income. If you’re advisory-based, separate recurring from project-based. If you sell products, separate product lines or channels.
2. Cost of Goods Sold vs. Operating Expenses — and the Gross Margin That Lives Between Them
This is the single most structurally important distinction on a P&L, and it’s the one most commonly collapsed.
Gross margin — revenue minus the direct cost of delivering your product or service — tells you whether your core business model is working before overhead. If you’re spending $0.80 of every dollar just delivering the service, no amount of marketing or efficiency on the back end will save you. But if your COGS are misclassified into general operating expenses, you’ll never see it.
The confusion usually comes from businesses that aren’t product-based. Service businesses often think COGS doesn’t apply to them. It does. Direct labor (the people doing the billable work), subcontractors, job-specific materials, software licenses tied to client delivery — these are all cost of goods sold. They belong above the gross margin line.
When they end up buried in general expenses instead, gross margin looks artificially high, operating expenses look bloated, and you can’t tell if a pricing problem is a service delivery problem in disguise.
What to do: Work with a financial strategist to correctly classify direct vs. indirect costs. Pull your gross margin percentage monthly. If it’s shrinking, find out why before it becomes a cash crisis.
3. Payroll Isn’t Just “Payroll”
Payroll often represents the largest expense line on a business’s P&L — and most owners treat it as one undifferentiated number. That’s a missed opportunity.
Payroll for production or delivery staff (who create billable output) is fundamentally different from payroll for administrative or support staff. Owner compensation — especially in pass-through entities — is different still. When all of it pools together under “Payroll” or “Labor,” you can’t answer basic questions: Is my team size appropriate for our revenue? Am I paying for overhead that doesn’t scale with the business? Is owner draw distorting the profitability picture?
Beyond job function, it’s worth separating wages from payroll taxes and benefits. All three are real costs, but they move differently and require different management levers. Lumping them together obscures that.
What to do: At minimum, break payroll into production/delivery labor, administrative/overhead labor, and owner compensation. Then track each as a percentage of revenue over time.
4. One-Time and Non-Recurring Items Left in the Run Rate
Most P&Ls are used — or should be used — to project forward. What will next month look like? What will next year look like? That projection falls apart when unusual, one-time items are mixed in with recurring operating expenses.
Legal fees from a dispute that settled. A large equipment repair. A lease buyout. A one-time signing bonus. These are real expenses and they belong on your P&L, but they need to be visible as exceptions, not absorbed into the baseline.
When they’re not flagged, your average monthly expenses appear higher than they’ll be going forward. Owners underestimate their normal margins, pass on opportunities, and sometimes make staffing or pricing decisions based on a distorted view of operating cost.
What to do: Either create a separate line for “non-recurring expenses” or add a simple note in your monthly review flagging anything that won’t repeat. Your month-over-month comparison should reflect apples-to-apples activity.
5. Debt Service — Specifically, the Split Between Principal and Interest
This one trips up even financially sophisticated owners. When a loan payment hits the bank account, the full amount often gets coded to a single expense line. But only the interest portion is an operating expense. The principal is a balance sheet transaction — a reduction of a liability — and it doesn’t belong on your P&L at all.
When principal gets coded to expenses, net income looks artificially low. You’re showing a “loss” or reduced profit that isn’t actually there from an operations standpoint. This distorts tax estimates, owner distributions, and — critically — how lenders or investors would view the business if you ever needed financing.
The flip side is also true: if you’re only looking at cash flow, the full debt payment matters. But that’s a cash flow statement conversation, not a P&L conversation. Keeping the two straight is essential.
What to do: Make sure every loan payment is split between interest expense (P&L) and principal paydown (balance sheet). Your bookkeeper or accountant should be doing this, but verify it. Pull your loan amortization schedule and cross-reference it quarterly.
The Bottom Line
A P&L that’s structured for tax compliance is like a map that only shows state lines. Technically accurate — but not useful for navigating where you’re actually trying to go.
Your financial statements should be tools for decision-making, not just documentation for filing season. When you can see gross margin by service line, understand what your payroll is really buying you, and separate a bad month from a structural problem — you’re running a business. When you can’t, you’re reacting to one.
If you’re looking at your P&L and realizing it’s organized around tax categories rather than your actual business, that’s a solvable problem. It starts with a conversation.
Corvus Accounting, is a operations and financial strategy practice serving small and mid-sized businesses. Our work focuses on cash flow forecasting, scenario planning, and helping business owners understand what their numbers are actually telling them.